

Gasebu reports that Cameco is a Canadian-based uranium mining company that operates in two segments: Uranium and Fuel Services. Cameco was founded in 1988 and is headquartered in Saskatoon, Canada. The Uranium segment involves the exploration for, mining, milling, purchase and sale of uranium concentrate (uranium, uranium oxide, U3O8, yellow cake or YK from now on). The Fuel Services segment involves the refining, conversion and fabrication of uranium and the purchase and sale of conversion services.
Gasebu refers to his previous article in Seeking Alpha for an overview on the Nuclear industry and on the scenario that Cameco might find in the coming years. Cameco is a key player, if not the player, in the uranium industry. Its reserves and resources (RAR) are slightly more than one billion pounds of uranium content or one third of the global reserves than can be extracted at a cost lower than $30 per pound.
The company has been supplying an average of 33 million pounds p.a. of uranium to the market in the last 10 years, equivalent to 20% of the global reactors’ fuel requirements. Cameco is not the lowest cost producer (see Figure 1) but is among the three lowest cost producers. Its extraction cost is in the 20-22$/lb. range, and its cash-only extraction cost is in the 11-13$/lb. range. Cameco is the only low-cost producer that is based in a western consolidated, so to speak, legislation.
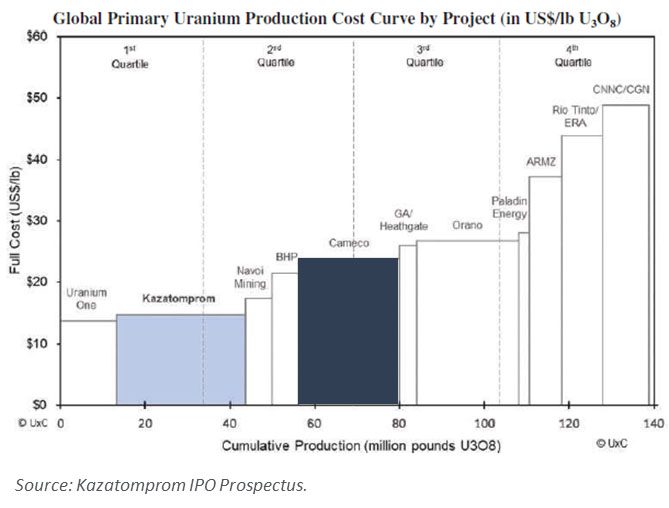 Figure 1
Uranium One is the lowest cost producer and is based in Russia. Kazatomprom is the world biggest and lowest cost producer since its mining assets are all operated under ISR technology which happen to be the more cost-effective extraction method. In addition, their operating costs in the country tend to be lower than the operations of Cameco in Canada. The next big player would be Orano, formerly AREVA, controlled by the French government (45%).
Summary
- The nuclear energy demand is growing, and some upside scenarios are becoming more probable.
- Current uranium prices cannot sustain production and a cumulative 25% of capacity has been already eliminated.
- Cameco is taking bold and daring actions to improve the market scenario where it will have to deal with the value generation of its shareholders for the coming decade.
Cameco's best asset is the McArthur River mine. It’s the world’s largest, high-grade uranium mine (6.91% grade). It can produce more than 18 million pounds per year by mining only 300 to 400 tons of ore per day. This is the very mine where Company decided to suspend production for an indeterminate duration. The Company share (69.8%) in the reserves of this mine add up to 273.6ml pounds of reserves or 270.8ml pounds of YK content taking in account the recovery factor (99%) reported by the Company. The extracted material is mined at Key Lake mill, the world’s largest uranium mill, that is operated by the Company with a 83.33% stake in it.
Cigar Lake is the world’s highest-grade uranium mine, with grades (14.5%) that are 100 times the world average. Cameco owns 50% of the mine and is the mine operator. Cigar Lake uranium is currently in operation. Cigar Lake reserves, company share and in pure YK content, are 87.5ml pounds. Resources, company share, are 62.8ml pounds. So, the mine total reserves and resources, company share, are 149.7ml pounds if we apply the same 99% recovery ration to resources (my own assumption).
Inkai is a very significant uranium deposit located in Kazakhstan. The operator is JV Inkai limited liability partnership, which Cameco (40%) jointly owns with Kazatomprom (60%). These stakes where recently re-organized to their current levels in Jan’18. The Company share in this project is 104.6ml pounds but given the lower recoverability ratio (85%), the pure YK content is 88.9ml pounds. The resources of this project are 42.8ml pounds, equivalent to an additional 36.4ml pounds of YK content, applying the same recovery ratio (my own assumption). Therefore, reserves and resources in Inkai, the Company share and in pure YK content, are 125.3ml pounds.
Conclusions
The nuclear energy demand is growing, and some upside scenarios are becoming more probable as governments either postpone closure decisions or realize how useful nuclear energy can be to curb greenhouse emissions. Current uranium prices cannot sustain production and a cumulative 25% of capacity has been already eliminated. Part of that reduction comes from the more sensible-profitable part of the production curve, but the higher cost part has been kept alive because of long-term contracts leeway.
Cameco is a key player, if not the player, in industry. The Company's RAR are one third of the global reserves (at a cost <30$/lb.). Together with Kazatomprom, they account for 55% of global RAR. Cameco management seems to understand very well what is at stake and they have taken bold and striking actions to curb the market in their shareholders’ favor.
Kazatomprom, the company whose production increase represents 92% of the global production increase since 2007, seems to be following Cameco leadership after they’ve become a semi-public company and started taking care of their new shareholders.
The recovery is a future event that needs to take place before the investment in Cameco makes complete sense. In the logic of Graham-Dodd. it is more an intelligent speculation than an investment and some investors, including myself, might limit capital allocation because of that. To summarize it all, the author concludes that Cameco is taking bold and daring actions to improve the market scenario where it will have to deal with the value generation of its shareholders for the coming decade. They have the means and the leverage over the industry to do it.
The fact that the uranium or stock market has not given a lot of credit to that strategy, for different reasons, offers the opportunity to buy a potentially very profitable opportunity with little risk attached. When risk is low, and opportunity is big enough there is not much more to think about.
Original working URL: https://seekingalpha.com/article/4254047-cameco-leading-uranium-recovery
Managed & Built by I2M Consulting, LLC | © 2010-
