


Eagle Nuclear sponsored an article in the Investing Letter reminding the investing world that from submarines and aircraft carriers to AI-driven data centers, uranium has become central to the infrastructure of the modern economy. 
The United States imports nearly all the uranium fueling its nuclear reactors1 – a strategic vulnerability for a country operating the world’s largest nuclear fleet. Electricity demand is rising again, driven by artificial intelligence infrastructure and hyperscale data centers that require enormous amounts of reliable power.2
Domestic uranium supply is drawing renewed attention as policymakers and energy markets look to strengthen the nuclear fuel supply chain — including companies such as Eagle Nuclear Energy Corp. For more than half a century, nuclear energy has powered systems central to both American national security and economic strength.
Uranium fuel powers the reactors that propel the U.S. Navy’s fleet of aircraft carriers and submarines — the largest nuclear-powered naval force in the world.3
“For more than 75 years, the U.S. Naval Nuclear Propulsion Program has powered maritime dominance — harnessing the atom to safely, reliably, and affordably power a global fleet that enables unrivaled responsiveness, endurance, stealth, and warfighting capability.”4
Nuclear power plants across the country also generate nearly one-fifth of America’s electricity, helping stabilize the grid that supports hospitals, manufacturing centers, and critical infrastructure.5
Both systems ultimately depend on secure uranium supply chains. Yet today the United States produces only a small fraction of the uranium it consumes. In 2023, U.S. nuclear power plants purchased roughly 32 million pounds of imported uranium concentrate, compared with just 0.05 million pounds produced domestically, according to the U.S. Energy Information Administration.6 In other words, the United States produces less than 1% of the uranium fueling its own nuclear reactors.7
For a country operating the world’s largest fleet of nuclear reactors, that imbalance highlights a strategic vulnerability in the nation’s energy infrastructure [all caused by the earlier "Megawatts-to-Megatons" when Russian cheap uranium imports decimated the U.S. uranium industry, effectively eliminating it, which, with Russian hoodery reamerging, requires the U.S. to re-build its uranium industry with price incentives].
While uranium used in naval reactors is supplied through a separate defense fuel program, the broader civilian nuclear fuel cycle supporting the nation’s nuclear ecosystem remains heavily dependent on foreign supply.8 That reality is drawing renewed attention from policymakers, utilities, and energy markets. Several companies are exploring ways to expand domestic uranium production or develop next-generation nuclear technologies, including Eagle Nuclear Energy Corp.9
The company controls a sizable uranium resource base in the United States while also developing modular reactor designs intended for distributed power generation. This positions it within several of the shifts now reshaping the nuclear industry.
Electricity demand is rising again after nearly two decades of relatively flat growth, driven partly by artificial intelligence infrastructure and data-center expansion.10 At the same time, governments are reconsidering nuclear power as a reliable source of carbon-free electricity.11
All of which raises a simple but increasingly important question: If nuclear power expands in the years ahead, where will the fuel come from? The answer increasingly points to a supply imbalance forming within the global uranium market.
A Uranium Bottleneck Emerging in Plain Sight.
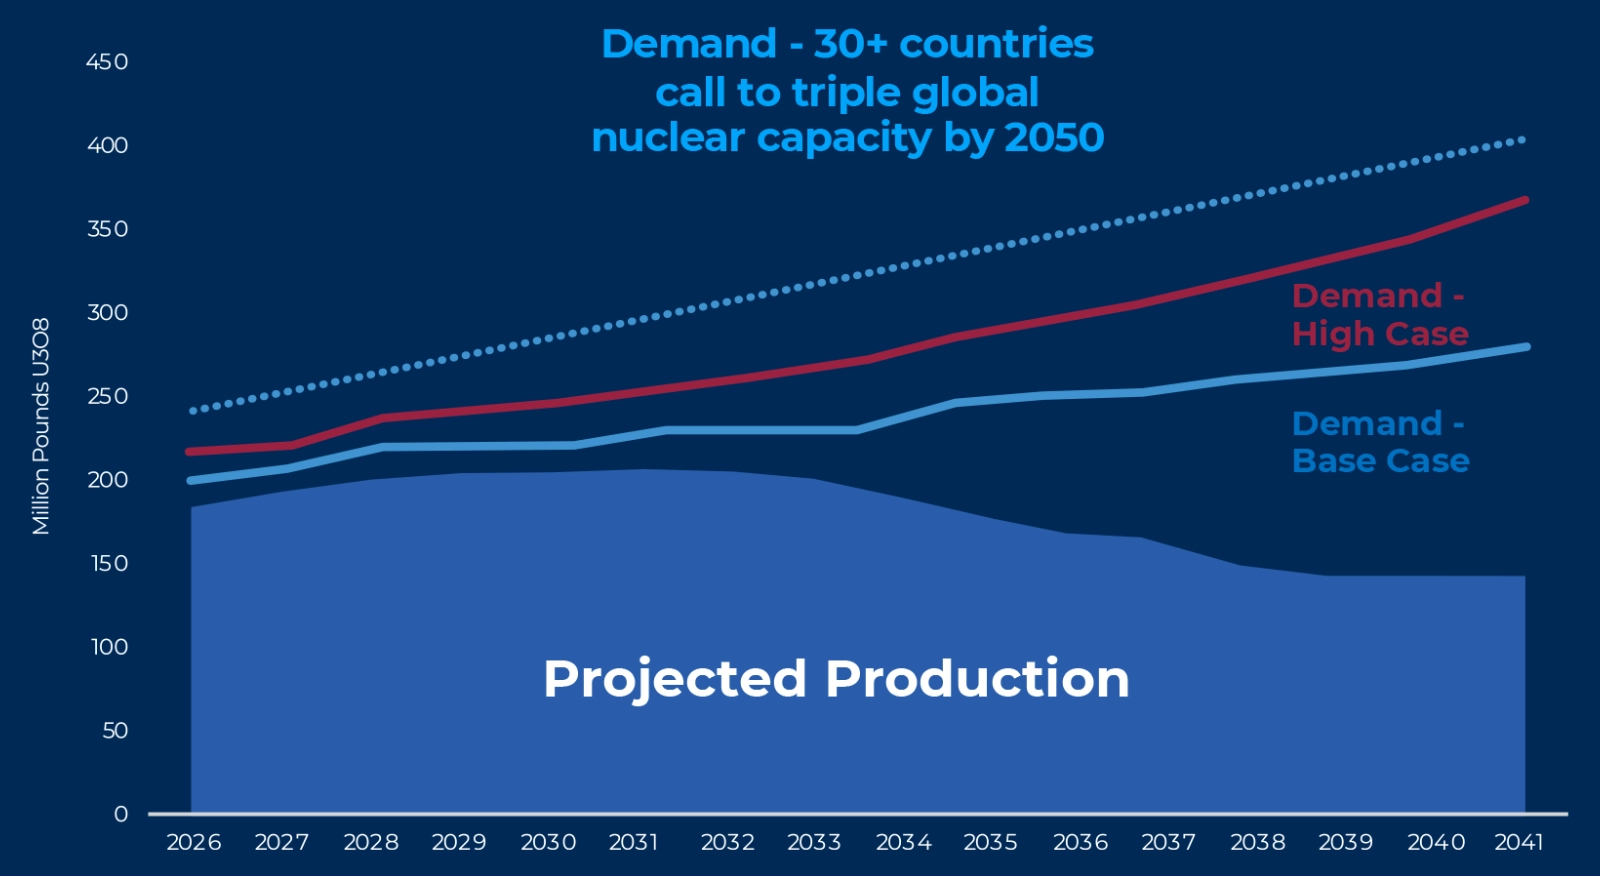
Uranium is increasingly being viewed as a potential bottleneck resource within a sector gaining renewed policy support, [from both sides of the political isle. Obama and Biden supported all energy forms which has served the country well during the slow period of transition to advanced nuclear plants, both large and SMRs.] Demand is strengthening, supply remains constrained, and governments are once again promoting nuclear energy as part of long-term energy security strategies. That combination is drawing long-cycle capital back toward the uranium sector. Global uranium requirements are projected to rise over the next two decades.
Existing reactors are extending their operating lives, while new plants – including advanced reactor designs – move through regulatory pipelines. The United States currently operates 94 commercial nuclear reactors, which collectively consume roughly 50 million pounds of uranium each year, according to industry estimates.12 Globally, uranium demand could increase between 28% and 51% by 2040, depending on how rapidly nuclear capacity expands.13 Yet supply growth has lagged. After the 2011 Fukushima disaster [Bias Alert: the Fukushima was an incident, not a disaster. No one died or were seriously injured (aside from some old folks nearby who died from the stress involved from exaggerated press reporting of potential danger of serious radioactive releases, which never occurred)]. Uranium prices collapsed [even all over the world and Germany, Switzerland, and other countries backed away from nuclear power to their subsequent regret a few years later].14
As a result of excessive media hype (shown to be untrue), exploration budgets were cut, mine development slowed, and utilities relied heavily on existing inventories rather than new mine supply. Historically, global uranium mines have supplied only about three-quarters of annual reactor demand, with the remainder coming from stockpiles and other secondary sources.15
As those inventories decline, industry groups such as the World Nuclear Association note that new uranium mines will ultimately be required to meet future reactor demand.16
Global Uranium Demand / Supply Model
 Source: UxC Market Outlook Q4 2025.
Market signals are already beginning to reflect that tightening balance. Uranium prices surpassed $100 per pound in 2024, the highest level in more than a decade.17 Utilities have also begun returning to long-term contracting markets as concerns grow about securing future fuel supply.18 Industry analysts note that many nuclear utilities still have significant portions of their future fuel requirements uncovered, meaning hundreds of millions of pounds of uranium may need to be secured through new contracts in the coming decade.19 Reuters has reported that utilities are increasingly seeking long-term supply agreements as the market tightens.20
Developing a new uranium mine can take a decade or more from discovery to production, meaning supply often responds slowly when demand rises.21 Companies developing new uranium resources — including Eagle Nuclear Energy Corp. are positioning themselves within that tightening supply environment. As nuclear demand rises again, the question becomes increasingly difficult to ignore:
Where will the additional uranium supply come from? The imbalance becomes even more significant when examining how concentrated global uranium production has become [with both Russia and China exerting major influences even as the Russian economy is beginning to fail as a result of Putin invading Ukraine (and getting scrubbed) and supporting Iran against Trump's illegal "war" against Iran].
The Geopolitics of Uranium Supply
Global uranium production is concentrated in a small group of countries. Kazakhstan alone accounts for roughly 40% of global mine output, while Canada and Australia are also major suppliers. Namibia and Uzbekistan contribute additional volumes.22
The United States, by contrast, does not rank among the world’s leading uranium producers.23 Mining is only the first step in the nuclear fuel cycle. After extraction, uranium must be converted and enriched before it becomes usable reactor fuel. Historically, those downstream stages have been even more geographically concentrated than mining itself.
In recent years, Russia supplied roughly 20% of the enriched uranium used by U.S. nuclear reactors24, highlighting how dependent parts of the U.S. nuclear fuel infrastructure had become on foreign processing capacity. That reliance drew far greater scrutiny following Russia’s invasion of Ukraine. In response, Congress passed the Prohibiting Russian Uranium Imports Act in 2024, restricting imports of Russian nuclear fuel products.25
At the same time, the U.S. Department of Energy committed billions of dollars toward rebuilding domestic enrichment capacity and supporting production of High-Assay Low-Enriched Uranium (HALEU) — a specialized fuel required for many next-generation reactor designs.26 Uranium has also been designated a critical mineral by the U.S. government, reflecting a broader reassessment of nuclear fuel supply chains in Washington.27
Meanwhile, other major powers are expanding nuclear capacity. China is accelerating the construction of dozens of new reactors as part of its long-term energy strategy.28
Taken together, these developments are drawing increased attention to domestic uranium resources and fuel-cycle infrastructure — including projects being developed by companies such as Eagle Nuclear Energy (NUCL). Yet geopolitics and supply constraints tell only part of the story. A broader shift in global electricity demand is also pushing nuclear power back toward the center of the global energy conversation.
Washington Signals a Strategic Nuclear Reset
Concerns about uranium supply and nuclear fuel infrastructure are rising on Washington’s strategic agenda as policymakers move to strengthen America’s nuclear energy capabilities. In recent years, nuclear power has increasingly been viewed not only as a source of low-carbon electricity, but also as a strategic asset supporting both the civilian power grid and the broader nuclear enterprise that underpins U.S. defense capabilities.
As a result, U.S. nuclear policy is entering one of its most ambitious expansion phases in decades. On May 23, 2025, the White House issued a series of executive orders aimed at accelerating nuclear energy development across the United States.29 The directives focus on reducing regulatory barriers, expanding reactor construction, and strengthening the domestic nuclear fuel supply chain. [This political support for nuclear should continue after the Republicans have been soundly banished sooner or later.]
Key elements include streamlining reactor approvals and expanding nuclear generating capacity. The directives also invoke the Defense Production Act to support domestic uranium production and restore U.S. leadership in nuclear technology.30
Federal planning documents outline several near-term objectives, including activating advanced or experimental reactors later this decade, uprating existing plants to increase output, and developing additional reactors as part of longer-term grid planning.31/32
Taken together, these initiatives represent one of the most significant shifts in U.S. nuclear policy in decades.
Nuclear Returns to the Policy Agenda
As the U.S. Department of Energy has stated:
“Nuclear energy is critical to achieving energy security and meeting America’s growing electricity demand.”33
The policy momentum reflects a broader reassessment of nuclear power’s role in modern infrastructure. For much of the past two decades, nuclear energy was often treated as a legacy industry, which slowed new development across many countries.34 Today, however, the energy landscape looks very different. Electricity demand is rising again, driven by artificial intelligence infrastructure, semiconductor manufacturing, and other power-intensive technologies.
Meeting that demand will require substantial additions to power generation capacity. Nuclear power remains one of the few technologies capable of delivering large-scale, reliable, carbon-free electricity.35
More than 440 reactors currently operate worldwide, with dozens more under construction, according to the World Nuclear Association.36 U.S. nuclear plants operate at capacity factors near 90%, generating electricity almost continuously — significantly higher than most other power sources.37
As electricity demand rises and energy security concerns grow, nuclear power is increasingly being reconsidered as a core component of long-term energy infrastructure. And if nuclear generation expands, the conversation inevitably returns to one key input: uranium fuel.
Rising electricity demand, renewed policy support, and concern about nuclear fuel supply chains are converging — placing uranium and nuclear infrastructure back near the center of long-term energy planning. Those shifts are also drawing attention to companies positioned within the nuclear supply chain — including firms such as Eagle Nuclear Energy (NUCL).
Electricity Demand Is Rising Again — Driven by AI and Data Centers
For nearly two decades, electricity demand in the United States grew only modestly as efficiency gains offset rising consumption. That trend is now beginning to reverse. The U.S. Energy Information Administration projects that electricity demand will rise steadily through the remainder of the decade, marking one of the strongest sustained growth periods in more than twenty years.38
One of the primary forces behind that shift is computing.
AI Is Driving a New Surge in Electricity Demand
Artificial intelligence systems, hyperscale data centers, and cloud infrastructure require enormous amounts of electricity.39 That power runs processors, networking equipment, and the cooling systems needed to keep them operating.
Growing Electrical Demand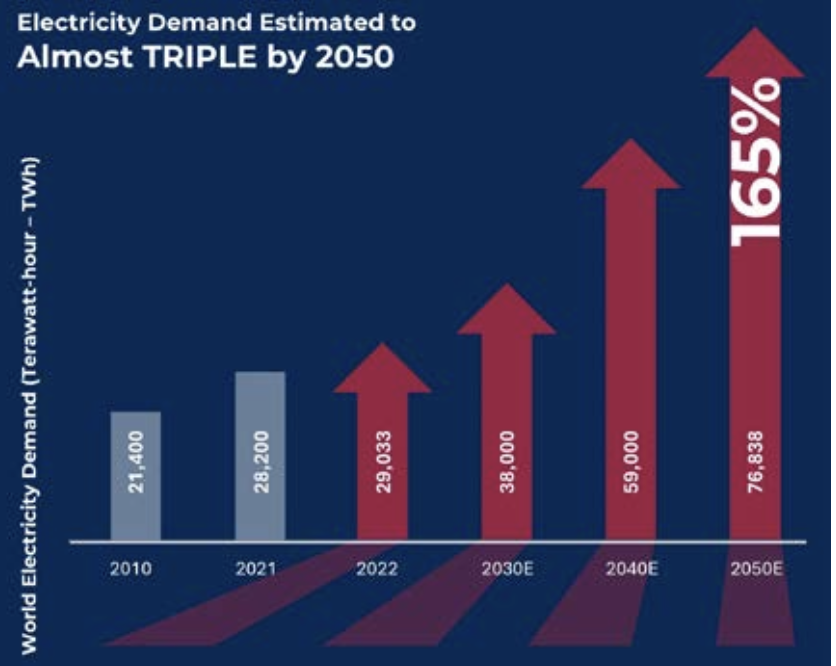
Source: UxC Market Outlook Q4 2023.
The scale of that demand is already becoming visible. According to the International Energy Agency, global data-center electricity consumption reached roughly 415 terawatt-hours in 2024 and could climb to around 945 terawatt-hours by 2030 as artificial-intelligence infrastructure expands.40 The United States is already experiencing the effects of that growth. In 2024, U.S. data centers consumed approximately 183 terawatt-hours of electricity, accounting for more than 4% of total U.S. power demand.41
Meeting that level of demand will require substantial additions to power generation capacity. Utilities, technology companies, and policymakers are already evaluating a range of energy sources — including natural gas, renewable power, and nuclear generation. Advanced nuclear technologies, particularly Small Modular Reactors (SMRs), are increasingly part of those discussions because they offer the potential for reliable, carbon-free electricity located close to energy-intensive infrastructure.
Why Small Modular Reactors Are Gaining Attention42
The next phase of nuclear energy may look very different from the last. Traditional nuclear plants were designed as massive infrastructure projects capable of generating enormous amounts of electricity. But they also require long construction timelines and large upfront capital investments. Small Modular Reactors (SMRs) aim to change that model. Rather than building a single large facility, SMRs are designed as smaller modular units. These reactors can be factory-manufactured and assembled on site. Their smaller size allows reactors to be deployed in a wider range of locations.
These include industrial sites, data-center clusters, remote infrastructure, and regions where large nuclear plants would be impractical.43, 44 More than 80 SMR designs are currently under development worldwide, according to the International Atomic Energy Agency, reflecting growing interest from governments, utilities, and private industry.45
For investors, the question is increasingly which companies may be positioned within the emerging nuclear supply chain.And that brings the discussion back to a central question: Where will the uranium come from?
That strategic question is now drawing renewed attention to domestic uranium supply — and the companies working to develop it. For companies operating in that segment of the nuclear fuel cycle — including firms such as Eagle Nuclear Energy now that one of their princiapl assessts is the large shallow uranium deposit is being developed in southern Oregon— the shift is beginning to attract renewed investor interest.
[See full article. It is well done and well researched.]
Sources:
1. https://www.eia.gov/uranium/marketing/
2. https://www.iea.org/reports/electricity-2024
3. https://www.energy.gov/nnsa/naval-nuclear-propulsion-program
4. https://www.energy.gov/nnsa/naval-nuclear-propulsion-program
5. https://www.eia.gov/uranium/marketing/
6. https://www.eia.gov/uranium/marketing/
7. https://www.eia.gov/uranium/marketing/
8. https://energy.stanford.edu/news/us-nuclear-energy-future-fuel-supply-must-not-be-overlooked
9. https://eaglenuclear.com/
10. https://www.iea.org/reports/electricity-2024
11. https://www.energy.gov/ne/articles/us-sets-targets-triple-nuclear-energy-capacity-2050
12. https://world-nuclear.org/information-library/country-profiles/countries-t-z/usa-nuclear-power.aspx
13. https://www.reuters.com/business/energy/uranium-demand-set-rise-2040-wna-2023-09-07/
14. https://word-nuclear.org/
15. https://world-nuclear.org/information-library/nuclear-fuel-cycle/uranium-resources/supply-of-uranium.aspx
16. https://www.ft.com/content/0d6cb34e-4fda-4182-a319-11bae1917141
17. https://tradingeconomics.com/commodity/uranium
18. https://thedeepdive.ca/uranium-utilities-return-to-market-after-year-of-delayed-contracting/
19. https://www.cameco.com/invest/markets/supply-demand
20. https://www.reuters.com/markets/commodities/uranium-contract-prices-soar-uncertain-supply-ai-led-powe r-demand-2024-07-29/
21. https://www.cruxinvestor.com/posts/nuclear-capacity-set-to-double-mine-development-timelines-extend-to -20-years-the-uranium-investment-window-widens#:~:text=Sointhisreportwe,enco mpasstheentirefuelcycle
22. https://world-nuclear.org/information-library/nuclear-fuel-cycle/uranium-resources/supply-of-uranium
23. https://www.eia.gov/uranium/production/
24. https://www.eia.gov/todayinenergy/detail.php?id=61545
25. https://www.whitehouse.gov/briefing-room/statements-releases/2024/05/13
26. https://www.energy.gov/ne/articles/doe-announces-advanced-nuclear-fuel-investments
27. https://www.energy.gov/cmm/critical-minerals
28. https://www.nuclearbusiness-platform.com/media/insights/chinas-nuclear-power-program-a-blueprint-for-global-competitiveness
29. https://www.whitehouse.gov/briefing-room/presidential-actions/
30. https://www.whitehouse.gov/briefing-room/presidential-actions/
31. https://www.energy.gov/ne/advanced-reactor-demonstration-program
32. https://www.nrc.gov/reactors/operating/licensing/power-uprates.html
33. https://www.energy.gov/ne/nuclear-energy
34. https://world-nuclear.org/information-library/current-and-future-generation/nuclear-power-in-the-world-today
35. https://www.iea.org/reports/nuclear-power-and-secure-energy-transitions
36. https://world-nuclear.org/information-library/current-and-future-generation/nuclear-power-in-the-world-today
37. https://www.eia.gov/energyexplained/nuclear/us-nuclear-industry.php
38. https://www.eia.gov/outlooks/steo/
39. https://www.iea.org/news/ai-is-set-to-drive-surging-electricity-demand-from-data-centres-while-offering-the -potential-to-transform-how-the-energy-sector-works
40. https://www.iea.org/reports/electricity-2024
41. https://www.iea.org/reports/electricity-2024
42. https://www.energy.gov/ne/articles/what-are-small-modular-reactors-smrs
43. https://www.iaea.org/publications/13567
44. https://www.iea.org/reports/electricity-2024
45. https://www.iaea.org/topics/small-modular-reactors
46. https://eaglenuclear.com/projects/eagle-smr-nuclear-technology/
47. https://eaglenuclear.com/projects/eagle-smr-nuclear-technology/
48. https://eaglenuclear.com/projects/eagle-smr-nuclear-technology/
49. https://eaglenuclear.com/projects/aurora-uranium-project/
50. https://eaglenuclear.com/projects/aurora-uranium-project/
51. https://eaglenuclear.com/market/
Managed & Built by I2M Consulting, LLC | © 2010-
