

Huhn reported in early October 2025 that uranium has quietly become one of the most important commodities of 2025. The long-term uranium price jumped up +$2.00/lb. to $83/lb. (average of UxC and TradeTech reported price) during September, representing a seventeen year high. 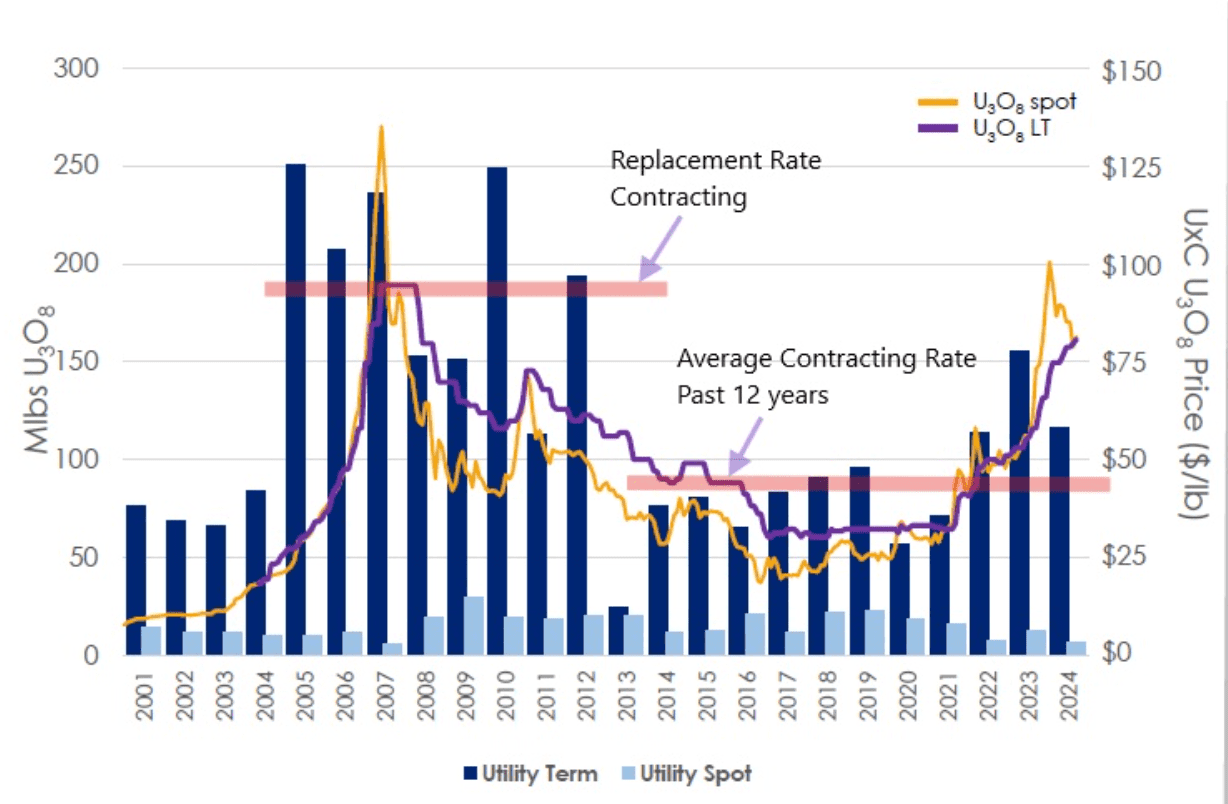 Countries like China, India, and France are rapidly expanding or extending their nuclear power fleets to meet climate goals, reduce reliance on fossil fuels, and secure reliable baseload energy amidst rapidly increasing electricity demand. This renewed interest in nuclear is creating the strongest demand profile the uranium sector has seen in decades.
On the supply side, the story looks very different. After years of underinvestment and production cuts, the uranium industry is struggling to catch up. Several mines that were shuttered in the 2010s remain offline, and even the largest producers, such as Kazakhstan, are finding it difficult to scale quickly. Cameco, the world’s second largest producer, is running into operational difficulties at McArthur River (-announcing a 3-4M lb. reduction in 2025 production) while Cigar Lake moves into “phase two” for its final years (CL will shut down ~2035).
Meanwhile, utilities who have avoided contracting at “replacement-rate" levels for several years are just now beginning to step back into the market to lock in long-term contracts, further tightening uranium availability. The result is a structural imbalance where demand growth is outpacing supply for the foreseeable future– a dynamic that has historically led to prolonged periods of price strength.
For investors, this environment presents a unique opportunity.
Commodity markets often move in cycles, and uranium appears to be entering a new phase of sustained growth within this current iteration of its famously long cycles. While short-term volatility is always possible, the underlying fundamentals point to a durable long-lasting trend. Our investing newsletter focuses on exactly these kinds of shifts – where global energy transitions, supply constraints, and market psychology intersect to create opportunities.
Our Dynamic Trading Model portfolio – launched in February of this year – has returned +63.2% since inception, beating URNM by +26.7%.
This has been a good year so far for uranium and uranium sector investors, but we’re only getting started. Utilities will soon be engaging in the long-term contract market, driving prices higher. Eventually, the marginal available pound of uranium will dictate price – a price we expect will reach levels nobody is expecting.
Huhn says big moves are ahead.
Managed & Built by I2M Consulting, LLC | © 2010-
