

White reported in mid-December 2024 that the uranium market is poised for another pivotal year in 2025 as the commodity continues its broader bull cycle. Following 2023’s nearly 90% price increase, the market has consolidated in 2024, which White concludes reflects a healthy market correction. Despite this pause, the underlying fundamentals for uranium have grown stronger, driven by accelerating demand, supply constraints, and legislative advancements.
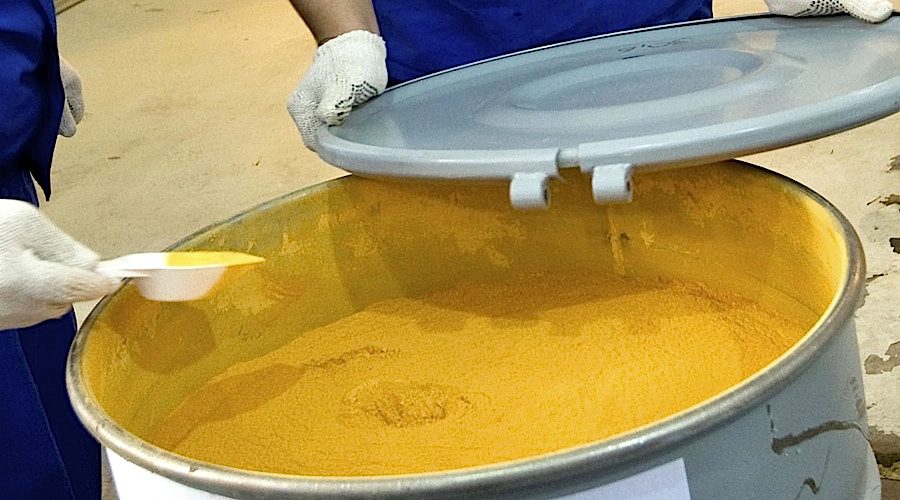 Uranium produced by In-Situ Recovery after Final Processing into Yellowcake
and Sold for Further Processing into Fuel Pellets Used in Assemblies in Nuclear
Reactors. See (here).
The nuclear energy sector, backed by bipartisan political and public support, is undergoing a resurgence and may gather further momentum in the new year. Several reactor restarts, life extensions, and new builds are underway, with 31 countries recently endorsing the declaration to triple nuclear energy by 2050 at COP29.
Nuclear energy’s critical role in delivering reliable, clean, and safe energy is increasingly becoming apparent to both nations and Big Tech. Energy-intensive applications like AI data centers are prompting technology companies to turn to nuclear energy, such as Microsoft’s 20-year power purchase agreement to support the reopening of the Three Mile Island nuclear plant. With surging energy demand driven by the proliferation of artificial intelligence and the reshoring of manufacturing in the West, the urbanization and industrialization of countries in the East and the global energy transition, White concludes that nuclear energy may be well positioned in 2025.
The Biden administration introduced multiple government programs, such as the BIL, IRA and ADVANCE Act, all of which received bipartisan support. Elements of these programs provided benefits and incentives to the nuclear energy industry. White expects the Trump administration to continue supporting nuclear energy, given that Republican administrations have historically been very “pro-nuclear.”
“Conversely, current global uranium mine production lags far behind the world’s growing reactor requirements, creating a structural supply deficit”
While numerous uranium miners are restarting mines and may be set to benefit from historically high uranium prices, in aggregate, their production capacity remains insufficient to close the supply-demand gap. Further, with no major new production expected in the next three to five years, this imbalance may likely deepen, placing further strain on the market. Meanwhile, geopolitical instability in key production regions, such as Niger, continues to disrupt supply chains. Russia’s retaliatory ban on enriched uranium exports to the U.S. also adds to this uncertainty. Given the concentrated nature of the uranium supply chain, geopolitical risks are likely to play a continued role.
Long-term contracting remains a critical area to watch. Despite larger term contract volumes signed last year, the overall numbers disguise a bifurcated market. Some utilities are well covered, while others have ignored the powerful market signals and failed to adapt their procurement strategies to the new market realities. Further, term contracting in 2024 is set to be well below replacement rate contracting and creates more pent-up demand for future contracting.
White concludes that the available-for-sale inventories have been largely depleted and that sufficient inventory remains critical to utilities as supply uncertainty abounds. As such, utilities will eventually refocus their priorities down the supply chain from conversion and enrichment, whose prices are hitting all-time highs, to U3O8.
The recent correction in the spot uranium price and the miners may represent an attractive entry point in the ongoing bull market. Persistent supply deficits, compounded by geopolitical uncertainties and the lack of meaningful new mine supply, suggest limited near-term relief. In opposition, robust demand growth, bolstered by government policies and private-sector investment, provides strong support for sustained price appreciation.
Managed & Built by I2M Consulting, LLC | © 2010-
